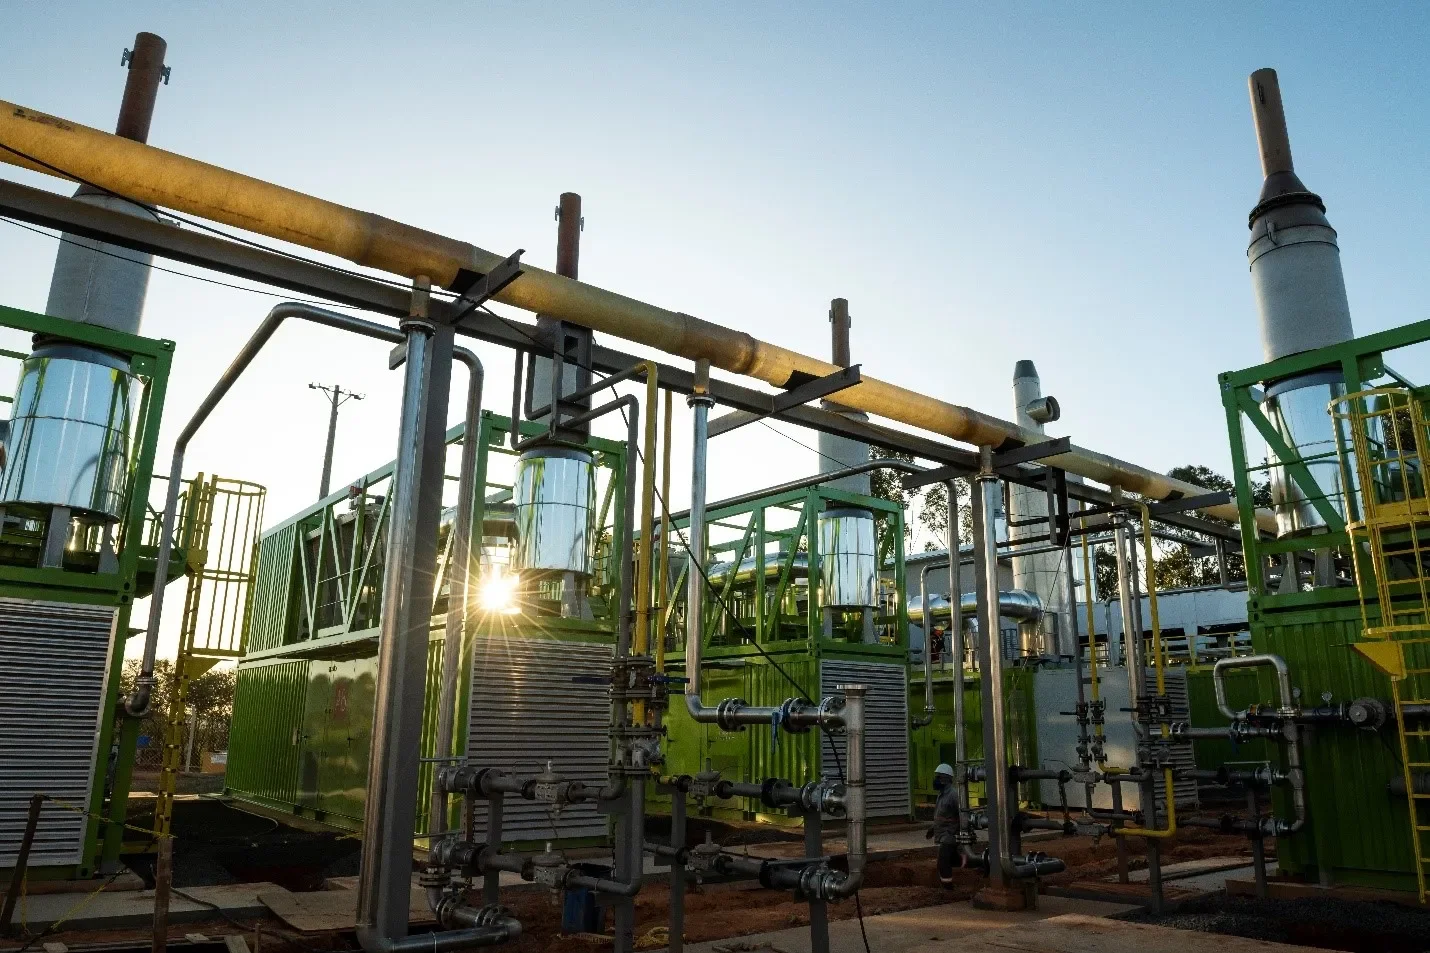
Compass Gás e Energia (PASS3) reported consolidated net income of R$ 591.1 million in 3Q26, up 36.8% from the same period in 2025. The result reflects higher EBITDA (earnings before interest, taxes, depreciation and amortization), offset by higher financial expenses, due to a larger debt balance, and by higher depreciation, due to the larger asset base of the distribution companies and new projects that began operating in 2026.
Adjusted EBITDA was R$ 1,508 million, an increase of 8.4% versus 3Q25. Reported EBITDA totaled R$ 1,636.5 million, up 22%. Net operating revenue was R$ 4.1 billion, down 3% versus 3Q25. Adjusted gross profit reached R$ 1,736 million, 6.7% above the prior year.
In the Marketing and Services (Edge) segment, normalized EBITDA was R$ 277.9 million, up 44.0%, with better performance in the on-grid business and the start of off-grid operations. The segment's EBITDA was R$ 421.6 million, driven by gains from load optimization. Edge sold 5.3 million m³ per day, up 21%. In distribution, adjusted EBITDA was R$ 1,258 million, up 2.0%, and the volume distributed fell 4.2%, to 14.8 million m³ per day.
Adjusted SG&A (selling, general and administrative expenses) fell 6.7%. The financial result was an expense of R$ 457.3 million, up 16.1%. Net debt stood at R$ 11,525 million and leverage (net debt/EBITDA) declined from 2.3x in 2Q26 to 2.2x in 3Q26. Investments totaled R$ 588.4 million, down 8.4%.
Compass declared R$ 495 million in dividends. Over the last 12 months, the total declared was R$ 1.1 billion, equivalent to a yield of 7.0%, calculated at a price of R$ 22.90 per share on September 30, 2026. The company also completed the repurchase of 3.2 million shares, for a total of R$ 72.8 million.
Is PASS3 worth investing in?
- Price
- R$ 21.06
- as of 11/11/2026
- Dividend yield
- 0.00 %
- P/L
- 13.08
- P/VPA
- 2.49