
Orizon (ORVR3) posted reported net income of R$ 55.7 million in 3Q26, the first quarter with three full months of Vital's results. Excluding the accounting effects of the merger, mainly the amortization of the purchase price allocation (R$ 67.4 million), adjusted net income was R$ 136.8 million. Adjusted net income was 21.8% below the R$ 174.9 million in 3Q25 pro forma and 32.7% above the R$ 103.1 million in 2Q26.
Adjusted net revenue totaled R$ 1,017.7 million (R$ 1.02 billion), up 13.9% from 3Q25 pro forma and up 3.7% from 2Q26 (R$ 981.7 million). Adjusted EBITDA (earnings before interest, taxes, depreciation and amortization) was R$ 347.5 million, with a margin of 34.1%, up 4.6% in one year and up 23.3% from 2Q26 (R$ 281.7 million). On an accounting basis, net revenue was R$ 1,090.3 million and EBITDA was R$ 322.6 million. Considering only the Orizon Legacy assets, adjusted revenue was R$ 366.8 million (+30.5%) and adjusted EBITDA was R$ 154.3 million (+18.0%).
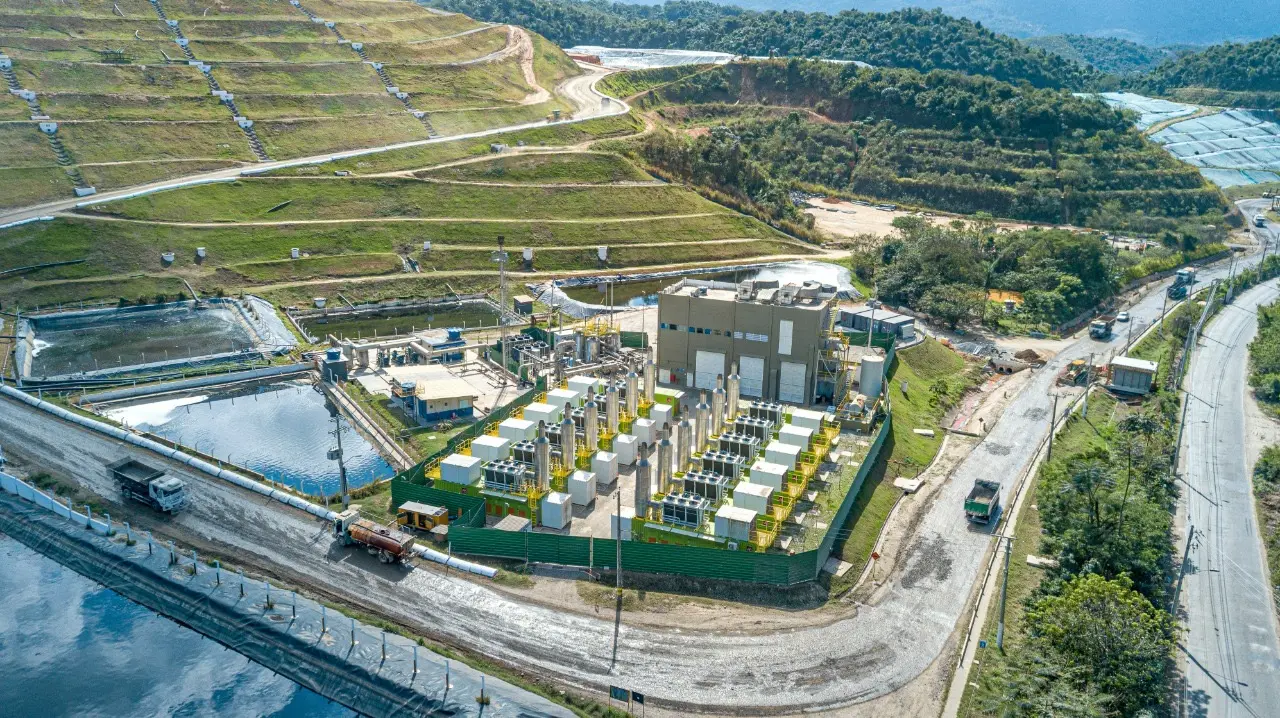
The eco-parks received 3,872.5 thousand tons of waste, up 5.8% in one year. The average gate fee (price per ton received) was R$ 90.6/t at Orizon Legacy, up 7.2%, and R$ 93.8/t at Vital. Biomethane production reached 189.4 thousand m³/day, up 45.4% from 2Q26. Revenue from carbon credits sold was R$ 28.8 million, up 105.7% in one year.
The company ended September with cash of R$ 1,683 million, gross debt of R$ 4,146 million and net debt of R$ 2,463 million, equivalent to 1.9x adjusted EBITDA (1.8x in 2Q26). Capex (investments) for the quarter was R$ 409.7 million. The R$ 500 million debenture issuance, made in October, is not reflected in these balances. It was split into R$ 150 million at CDI + 1.40% per year for 2 years and R$ 350 million at CDI + 1.75% per year for 7 years.
During the period, Orizon signed the purchase of 51% of the Rondonópolis Landfill (MT) for R$ 45.4 million and increased its stake in Ecourbis from 63.3% to about 69.1%, for R$ 69.2 million. The company also approved a 1:4 stock split and elected Dalton Assumção Canelhas Filho as Chief Operating Officer. Orizon also reported that the exercise of the subscription warrants (ORVR11) could generate potential capitalization of about R$ 1.0 billion, with exercise expected between May and September 2027.
Is ORVR3 worth investing in?
- Price
- R$ 19.32
- as of 11/11/2026
- Dividend yield
- 0.00 %
- P/L
- 211.17
- P/VPA
- 2.19