On Wednesday, October 21, 2026, Moody’s Local Brasil affirmed the AA.br issuer rating of PetroReconcavo (RECV3) and the AA.br ratings of the company’s 1st, 2nd, 3rd and 4th debenture issuances (debt securities issued by the company), all with a stable outlook. The decision takes into account the company’s performance over the 12 months ended June 2026 (LTM 2Q26) and the maintenance of moderately low leverage and cash generation that the agency considers robust.
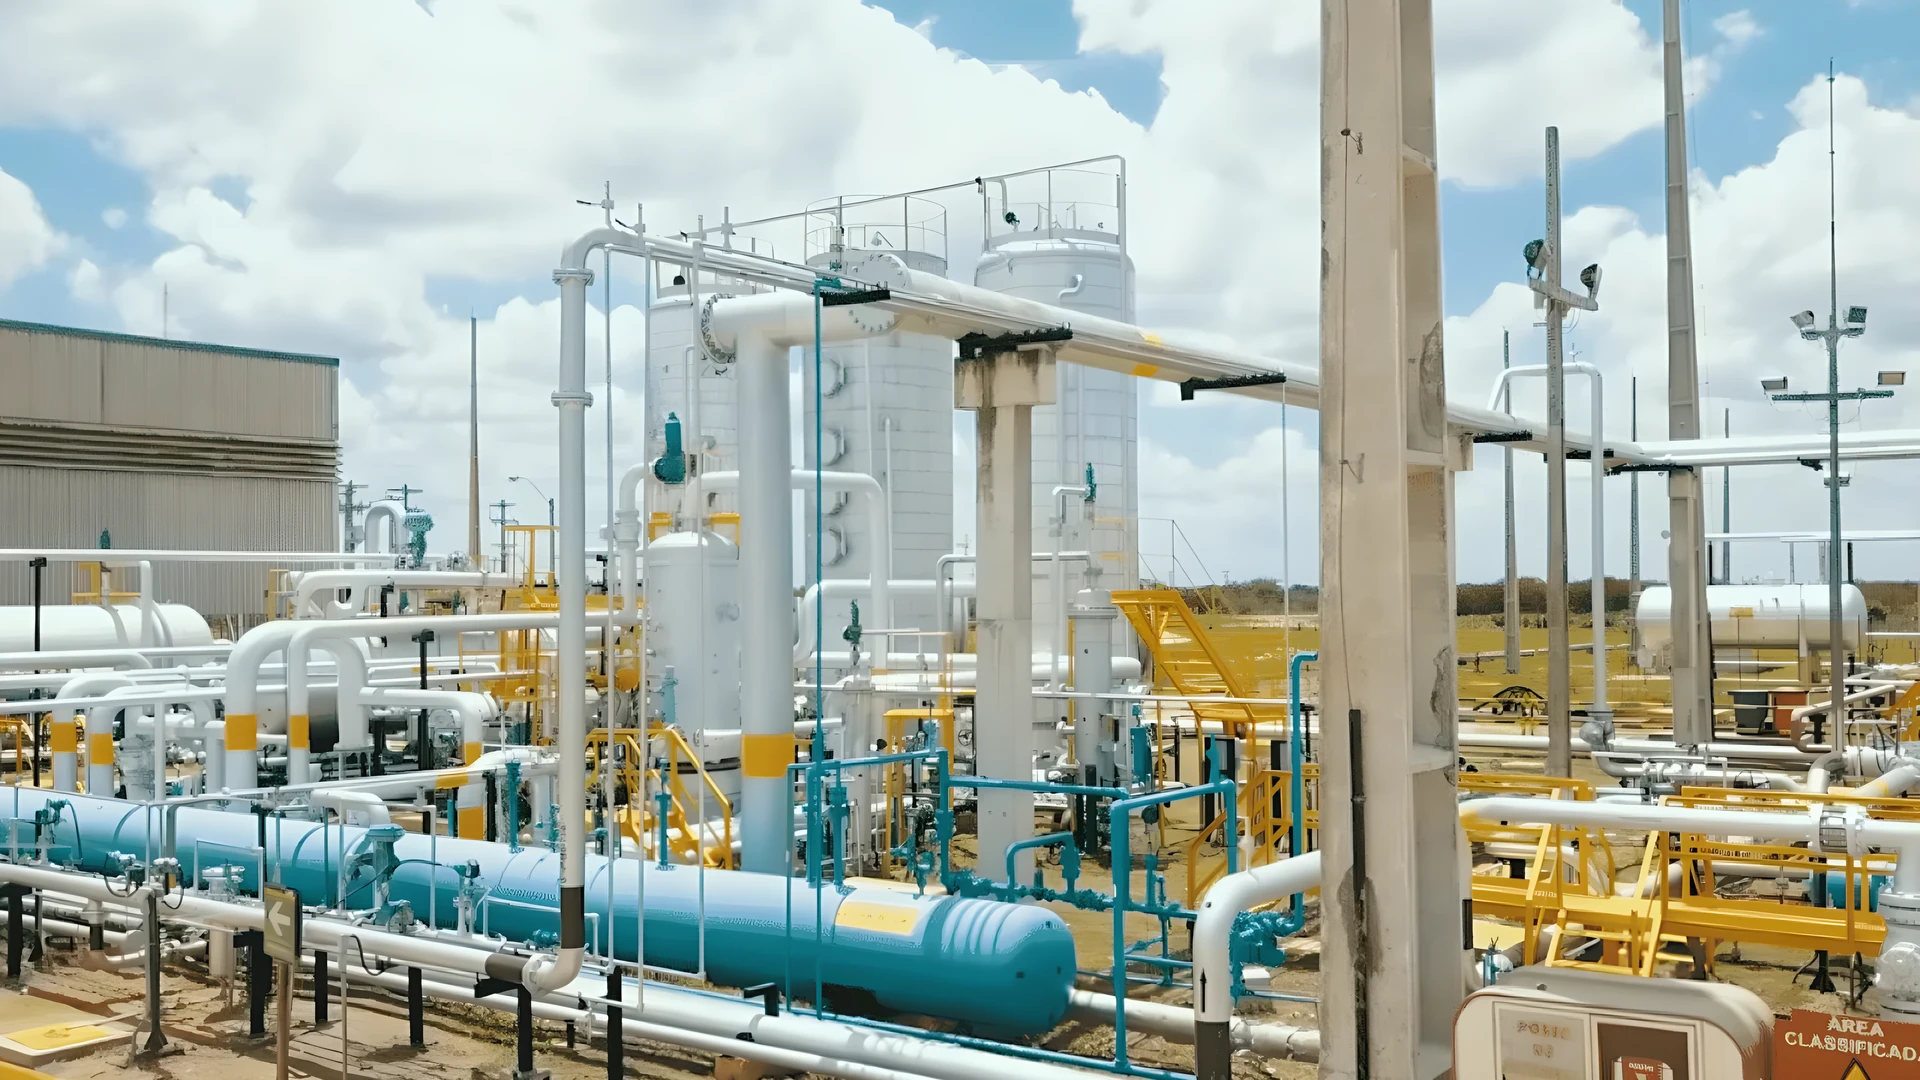
According to Moody’s Local Brasil, the cost profile remains competitive, supported by the vertically integrated structure and the track record in the recovery of mature onshore fields, in addition to a conservative financial policy. On the other hand, the rating factors in the company’s moderate operating scale, with average production of 24.1 thousand barrels of oil equivalent per day in 2Q26, down 12% from the same period in 2025, and its dependence on third-party infrastructure for processing and transporting production.
In LTM 2Q26, PetroReconcavo posted net revenue of R$ 3.0 billion and gross profit of R$ 957 million, compared with R$ 3.2 billion and R$ 1.0 billion in 2025, respectively. The adjusted EBITDA margin (earnings before interest, taxes, depreciation and amortization), which includes financial income, was 47.3% in LTM 2Q26, practically in line with the 47.4% in 2025 and below the 51.9% in 2024. Production was concentrated in the Potiguar and Bahia assets, which accounted for 49% and 51% of total output in August 2026, respectively.
In June 2026, PetroReconcavo had cash and cash equivalents of R$ 321.0 million and financial investments of R$ 1.3 billion, totaling around R$ 1.6 billion in available liquidity, covering 16 times the short-term gross debt of R$ 99 million. Gross debt adjusted by Moody’s Local Brasil totaled R$ 3.2 billion, with gross leverage of 2.3 times EBITDA and net leverage of 1.1 times, with no material principal maturities until 2028.
The stable outlook reflects the agency’s expectation that PetroReconcavo will maintain stable operating performance, cash generation sufficient to cover investments, and adjusted gross leverage between 2.0 and 2.5 times, with adjusted interest coverage between 1.5 and 2.0 times. Moody’s Local Brasil notes that a sustainable increase in production, with stable reserves and gross leverage below 2.0 times, could lead to a rating upgrade, while leverage sustainably above 3.0 times, negative free cash flow with no prospect of recovery, deterioration in liquidity, or a more aggressive financial policy could result in a downgrade.